Blues Hwy Benefits

Blues Hwy Benefits Independent Medicare guidance · Mississippi

A free book for your next chapter

Free book for Delta neighbors turning 65

Turning 65? Your Medicare window opens months before your birthday.
Get the free book that walks you through it.

I'll mail you a printed copy of Medicare Breakdown, postage paid, and you can start reading the digital edition today.

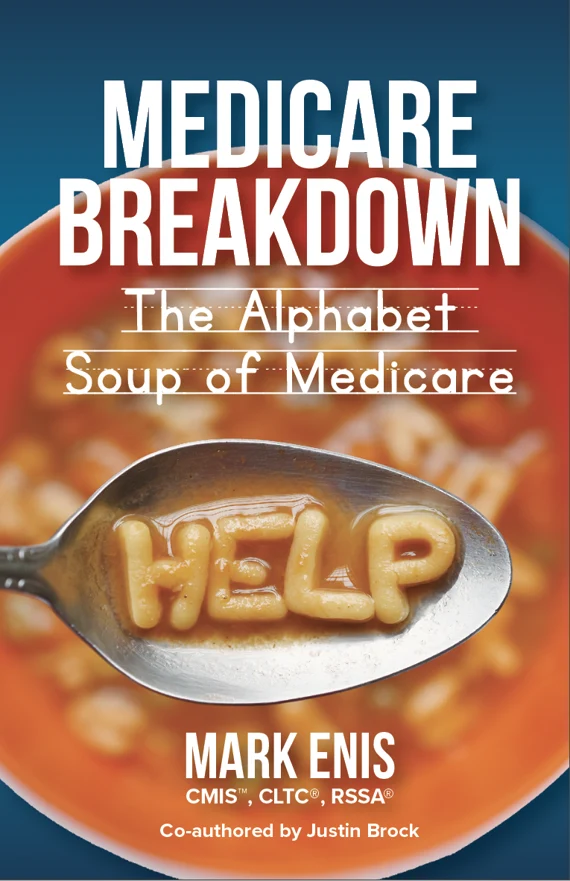
Medicare Breakdown: The Alphabet Soup of Medicare, by Mark Enis with Justin Brock

Medicare Breakdown:
The Alphabet Soup of Medicare
By Mark Enis, with Justin Brock

Inside, you'll find:

  • Who's enrolled automatically at 65, and who isn't (page 21)
  • How signing up for Part B too early can cost you (page 26)
  • Why Advantage and a Supplement aren't the same thing (page 28)

Printed copy + postage + digital edition. Your cost: $0.

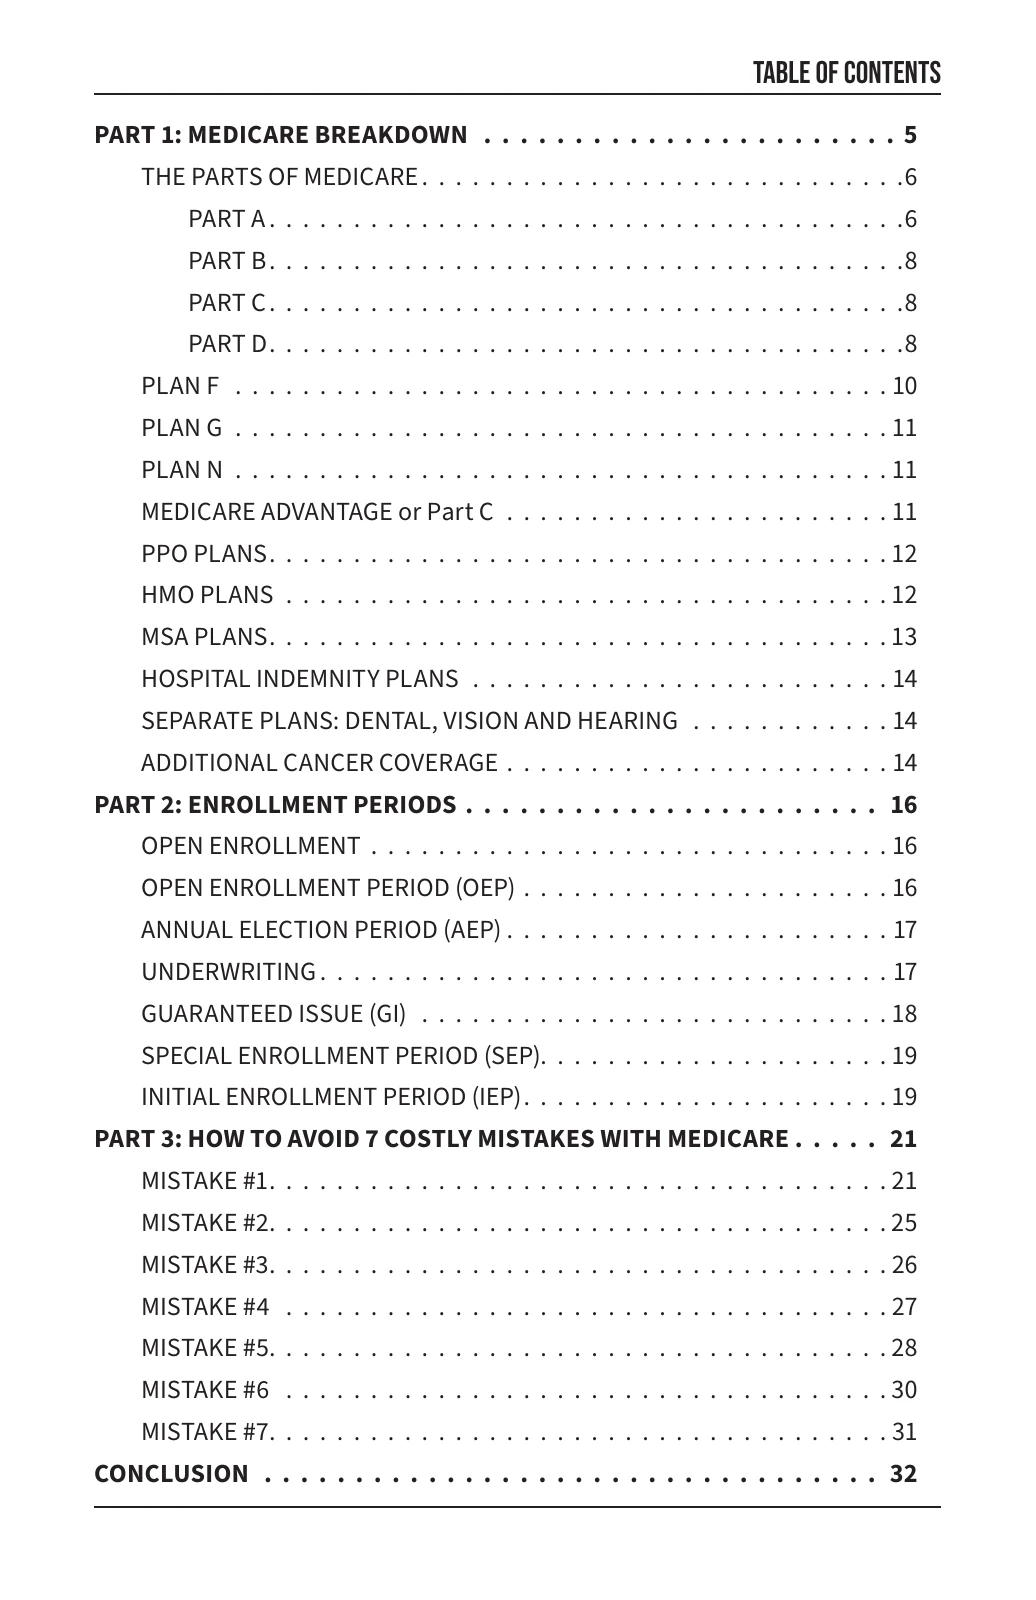
Look inside: see a real page from the book

The actual contents page—not a mockup. Open a larger view.

Actual contents page: Medicare Breakdown, Enrollment Periods, and How to Avoid 7 Costly Mistakes with Medicare

Where should I mail your free book?

I'll mail it free, and you can read the digital copy today. * Required

When do you turn 65?
Have you started receiving Social Security benefits? (It can affect whether Medicare Part B starts automatically.)

Free postage. No purchase required.

By requesting the book, you ask for the digital copy and useful Medicare emails. Unsubscribe anytime.

Written by Mark Enis, with Justin BrockPlain-English Medicare educationIndependent agency, not a government program

If your mailbox is filling up, this is for you

You were looking forward to your next chapter.
Not a second job figuring out Medicare.

Somewhere between the birthday mail, the television commercials and the advice from people who mean well, a simple question gets buried:

“What do I actually need to do before I turn 65?”

You want to keep seeing the doctors you trust. Keep getting the prescriptions you need. Understand what you'll pay. And make sure you don't miss something important that nobody bothered to explain.

Instead, you're handed an alphabet soup. Part A. Part B. Part C. Part D. A Supplement. An Advantage plan. Enrollment periods that sound alike but don't do the same thing.

Then somebody says, “Just get what I have.”

But they may have different doctors, different prescriptions, different job coverage and a completely different budget. The decision that worked for them isn't automatically the decision that fits you.

You don't need to become an insurance expert. You do need a clearer starting point. That's why I'm offering you this book.

Mail Me My Free BookFree printed book. Free postage. Digital copy included.

The mistake starts before the plan choice

The first question isn't “Which plan?”
It's “What applies to me?”

A plan brochure can tell you about a plan. It cannot tell you everything about your timing, your employer coverage or what needs to happen before your current insurance ends.

If you're still working, you may be wondering whether Medicare is something you need now or something you can delay. If you're retiring, you may be trying to line up one coverage end date with another coverage start date.

And if you haven't started collecting Social Security, you may be wondering whether your Medicare enrollment will happen automatically.

Those are not small details. They're the foundation. Getting them wrong can mean an unwanted gap in coverage, paying for coverage you didn't need yet, or a late-enrollment penalty when one applies.

This isn't a reason to panic. It's a reason to get informed before you act.

Understand your timing.

Understand your choices.

Then make your decision.

That's a much better place to begin than picking a familiar name from an envelope and hoping everything else works itself out.

Mail Me My Free BookStart with information, not an insurance application.
Mark Enis seated at a table, ready for a conversation
Mark EnisRSSA®, CLTC®, CMIS™Healthcare Coverage Specialist
Dublin, MS · By appointment

A personal note from Mark

I'd rather help you understand Medicare than ask you to rush into it.

Hi, I'm Mark Enis.

I went all-in on a hospitality business just before COVID. When the world shut down, I lost it. That's how I ended up in insurance, and it's why I take planning seriously: life can change faster than you expect.

Turning 65 is that kind of moment. It's a lot easier to get your questions answered before the deadlines than after them.

Requesting this book isn't agreeing to buy insurance. It's a chance to sit down, read and get your bearings first.

I wrote Medicare Breakdown with Justin Brock to give people a plain-English way into a subject that can feel unnecessarily complicated.

My office is in Dublin, MS, with meetings by appointment. I help people across Mississippi by phone and online, with in-person appointments in the Delta. I'm an independent insurance agent, not Medicare or Social Security.

If you want personal help after reading, I'm here. If you'd rather read first and make notes before talking to anybody, that's fine, too.

You should be able to ask a question without feeling like you've already agreed to a sale.

Mark Enis
A look inside your copy

A real book.
One you'll come back to.

Start with the parts of Medicare. Get your bearings on enrollment. Then work through common mistakes before making your own decisions.

Read a section with your spouse. Put a note beside something you want to ask. Keep it within reach when the next envelope arrives.

FROM THE TABLE OF CONTENTS

  1. PART 1 · PAGE 5Medicare Breakdown
  2. PART 2 · PAGE 16Enrollment Periods
  3. PART 3 · PAGE 21How to Avoid 7 Costly Mistakes with Medicare

Section titles from the book, not a separate checklist or a sample chapter.

Look inside: see the actual contents page

This page is from the book you'll receive. Open a larger view.

Actual table of contents from Medicare Breakdown, with sections on Medicare, enrollment periods and seven costly mistakes

Open the book. Start connecting the dots.

Seven things worth understanding
before you choose your coverage.

Not more insurance jargon. The practical questions underneath it.

In the book: page 5

The letters finally have a job description.

What does Original Medicare cover? Where do prescription drugs fit? What does Medicare Advantage replace, and what is a Medicare Supplement supposed to supplement?

Once you understand how the pieces fit together, you can stop treating every unfamiliar term as another separate decision. The book gives you a foundation for the conversations that come next.

In the book: page 21

Your birthday matters. So does your situation.

Turning 65 is an important starting point, but it doesn't tell the whole enrollment story. Current job coverage, Social Security and retirement timing can change what you need to do.

Learn the basic enrollment framework so you know which questions to ask before deciding to sign up or wait. A neighbor's experience is not a substitute for checking your own circumstances.

In the book: page 26

Still working? Don't confuse “I have insurance” with “I can safely wait.”

Coverage from your or your spouse's current employment may let you delay Part B. Employer size and the type of coverage matter. Retiree coverage and COBRA are not the same as current-employment coverage.

Before you assume the insurance card in your wallet answers the Medicare question, understand what needs to be checked. That one conversation can be more useful than another afternoon of comparing advertisements.

In the book: page 28

Two coverage paths. More than a monthly-price difference.

Original Medicare with a Supplement and separate drug coverage works differently from Medicare Advantage. Networks, referrals, cost-sharing and the way you receive care can differ.

Start by understanding those differences. Then look at how the options fit the doctors, prescriptions and budget you actually have, instead of choosing solely by a premium or a familiar company name.

In the book: pages 27 and 31

A prescription plan is not just another letter.

Drug coverage deserves its own attention. What works for one person's medications and pharmacy may not work the same way for yours. Premiums are only one part of that picture.

The book introduces how drug coverage fits into Medicare and why timing matters. When you're ready to compare, bring your own medication list rather than relying on somebody else's plan experience.

In the book: pages 16 and 25

“I can change it later” isn't a complete plan.

There are different enrollment windows for different decisions. Annual Enrollment is not the same as your initial Medicare enrollment, and it doesn't recreate your Medigap Open Enrollment Period every year.

Understand that distinction before assuming every decision has the same do-over. You don't need to memorize every rule. You need to recognize when to stop and ask a question.

In the book: page 30

Know what Medicare doesn't solve, too.

Having Medicare doesn't mean every healthcare expense disappears. Premiums, deductibles, copays and services Medicare doesn't cover still belong in the conversation.

A clearer view of the gaps helps you ask better questions and set more realistic expectations. That's more useful than being surprised after you've already made your choice.

Mail Me My Free BookRead at your own pace. Underline what matters. Keep it handy.
Mark Enis and his family together outdoors
My family. A reminder of what planning is really for.

There's a life on the other side of the paperwork

The goal isn't to spend more time thinking about insurance.

It's to get the important questions answered so you can get back to the people and plans that matter to you.

For me, that's my family. For you, it might be more time with the grandkids, a retirement you've worked toward, or simply enjoying an ordinary day without an unanswered coverage question hanging over it.

You don't need to share my circumstances to deserve clear answers about yours. Start with the book. Get your bearings. Then decide what help you want next.

Recognize yourself?

“I know I need to deal with this.
I just don't know where to start.”

Maybe your birthday is months away and you'd rather get ahead of the mail. Maybe you're planning to work past 65 and don't want to pay for something before you need it. Maybe retirement is close enough that coverage dates are suddenly a real concern.

Or maybe you're the spouse doing the reading because somebody in the house has to make sense of all this.

You don't have to have your situation figured out before requesting the book. The point is to help you start figuring it out.

  • You can be completely new to Medicare.
  • You can still be covered through work.
  • You can be planning ahead rather than ready to enroll.
  • You can want information before you want a conversation.

Real deadlines. Not a countdown clock.

Your timeline deserves more
than “I'll look at it later.”

Here are three reasons to get your bearings before you're making decisions in a hurry.

YOUR FIRST MEDICARE WINDOW

Generally, seven months.

Your Initial Enrollment Period generally includes the three months before your 65th birthday month, your birthday month and the three months after. If your birthday is on the first, that window shifts a month earlier.

When you enroll can affect when coverage starts. Don't assume “sometime around my birthday” is specific enough.

Choose your birthday on the request form and you'll see the months your window generally covers.

STILL COVERED THROUGH WORK?

Check before you delay.

Current-employment coverage may give you a different route. Employer size and coverage type matter, and you should check with the employer benefits administrator before deciding to wait.

The fact that somebody else delayed Medicare without a problem doesn't establish whether you can do the same.

MEDICARE SUPPLEMENT TIMING

A window that doesn't repeat annually.

Your six-month Medigap Open Enrollment Period starts the first month you're 65 or older and enrolled in Part B. Outside it, different underwriting or guaranteed-issue rules may apply.

The October 15–December 7 Annual Enrollment Period for Medicare Advantage and drug coverage is not a replacement for that window.

Enrollment information: Medicare.gov: when to sign up · Medigap enrollment · Annual Enrollment. General education, not an individual enrollment determination.

Here's exactly what I'm offering you

A book you can hold.
A copy you can open now.
A place to begin.

This isn't a free chapter that ends with a checkout page. You're requesting the book. There is no shipping charge waiting at the last step.

You don't need to give me a Medicare number, a Social Security number or a credit card. Just the details needed to send your copy and useful follow-up emails.

Your free printed Medicare Breakdown book
01 / THE PRINTED BOOK

Medicare Breakdown

A physical copy of The Alphabet Soup of Medicare. Read it away from a screen, make notes and come back to the parts that apply to you.

FREE
02 / THE MAILING

Postage included

Tell me where to send it. There's no shipping-and-handling payment to make and no card information to enter.

FREE
03 / THE DIGITAL EDITION

No need to wait to start reading

Download the 2026 digital edition after your successful request. A separate confirmation email includes the download link.

FREE

Your cost: $0

Mail Me My Free BookOne short form. Printed book, postage and digital edition included.

A fair question

“Why would you send me a book for free?”

Because helping you understand Medicare is a sensible place to start a relationship.

I'm an insurance agent. If you eventually decide you want help comparing coverage and enrolling, I'd like the opportunity to help. That's the business reason behind the offer, and I'd rather be straightforward about it.

But receiving a book doesn't obligate you to buy a policy, book an appointment or let me make the decision for you.

You'll receive the digital copy and useful Medicare emails. You can unsubscribe anytime. The book request does not ask for your phone number.

In other words: you can say yes to learning more without saying yes to an insurance purchase.

Education first. A conversation when you're ready.

Don't send private medical details, a Medicare number or a Social Security number in the request form. None of those are needed to mail your book.

From this page to your next step

Here's what happens after you say yes.

  1. Tell me where to send it.

    Enter your mailing address and email. Your 65th birthday helps put the timing in context. No phone number is needed.

  2. Start reading right away.

    After a successful request, download the digital edition. Your request also gives me the information to mail the printed copy.

  3. Read first. Ask questions next.

    Keep a list of anything you want to discuss. You'll receive useful Medicare emails, with an unsubscribe option whenever you need it.

  4. Choose whether you'd like personal help.

    Right on the confirmation screen, you can pick a time for a free, 30-minute Medicare Roadmap Session with Mark by phone or Google Meet. Talk through your own situation when you're ready. It's optional.

Mail Me My Free BookOne request. Printed book + postage + digital edition included.

Before you make your decision

Let's answer the questions
you may still be asking.

Which edition will I receive?

The 2026 edition of Medicare Breakdown. Use it as a foundation for understanding Medicare, not as a statement of 2027 or 2028 costs or available plans. Confirm rules, costs and plan details for your coverage year before enrolling.

Does my confirmation mean the printed book has shipped?

No. It confirms your mailing request. You can download the digital copy right away; the printed copy will be mailed separately. If your mailing address needs correcting, email mark@blueshwybenefits.com.

Is the book really free, including postage?

Yes. Your printed book, postage and digital copy are free. No payment information is needed, and requesting the book does not enroll you in an insurance plan.

Do I have to schedule an appointment or buy insurance?

No. Read the book first. If you want help with your own situation afterward, you can pick a time on the confirmation screen for a free, 30-minute Medicare Roadmap Session with Mark by phone or Google Meet. Booking is optional. There is no obligation to buy.

What if I am still working at 65?

The book is for you, too. Coverage through your or your spouse's current job can affect when you need Medicare. Employer size and the type of coverage matter, so check your situation before deciding to delay.

Is this a government program?

No. Blues Hwy Benefits is an independent insurance agency, not connected with or endorsed by the U.S. government or the federal Medicare program.

Who wrote the book?

Mark Enis, with Justin Brock. The title is Medicare Breakdown: The Alphabet Soup of Medicare.

Your next chapter should feel like yours

You don't have to decide on a plan today.
Just give yourself a better place to start.

Picture sitting down with one understandable explanation instead of another pile of competing advertisements. You can read, mark a page and finally put a name to the question you've been trying to ask.

That doesn't mean a book can make every decision for you. It means you don't have to go into those decisions cold.

My offer is simple: I'll send you a printed copy of Medicare Breakdown, cover the postage and include the digital edition. You pay nothing for the book or mailing.

You don't need to be ready to enroll to ask for it.

Just a useful first step while you still have time to think, ask questions and understand what comes next.

Mail Me My Free BookTell me where to mail it. Start reading the digital copy right away.

P.S. Still working at 65? Don't assume this doesn't apply to you. Knowing what to check before you delay can matter just as much as knowing how to sign up. Get the book, read the basics and check your own situation before making that call.

Call(662) 339-3532Get Help

YOUR FREE MEDICARE BOOK

Don't leave Medicare to guesswork.

Medicare Breakdown book cover

Get the basics before you enroll—or decide to wait. I'll send you Medicare Breakdown (2026 edition), cover the postage and include the digital copy.

No purchase. No appointment required. No payment information.

Double-check your mailing address

You entered

A Google address check is not a guarantee of delivery. If we cannot confirm your address, Mark will need to review it before mailing.